· By Juan Murray
Things to Consider When Buying a House in Boston
The things to consider in buying a house come down to five factors: what you can truly afford, the property's condition, the location's resale strength, the total cost beyond the price, and your walk-away terms if something is wrong. Everything else is detail work around those five.
What should you consider when buying a house in Boston?
Weigh what you can truly afford, the property's condition, the location's resale strength, the total cost beyond the price, and your walk-away terms if something is wrong. This guide turns those factors into a decision framework: financial readiness, the red flags that should slow you down, the rules of thumb buyers ask about most, and the Massachusetts rules that shape Boston purchases, including lead paint and inspections. For what you'll pay at the closing table, see closing costs for Boston buyers. Before you tour with an agent, see buyer representation agreements in Massachusetts. The Boston buyer guide walks through the whole process.
Key Takeaways
- Most purchase decisions come down to five factors: affordability, condition, the location's resale strength, total cost beyond the price, and your walk-away terms.
- Buyer closing costs in Massachusetts commonly run about 2% to 5% of the price, or $10,000 to $25,000 on a $500,000 purchase.
- For contracts signed after October 15, 2025, sellers can't condition acceptance on a buyer waiving or limiting a home inspection on 1 to 4 unit homes, condos, and co-ops.
- For homes built before 1978, the seller must give you the Massachusetts Property Transfer Lead Paint Notification before you sign a Purchase and Sale Agreement.
- Boston homes on the market more than 60 days sold for a median 92.6% of their original price, so a listing that has been sitting often leaves more room to negotiate.
What Is the 3-3-3 Rule for Buying a House?
The "3-3-3 rule" is an informal budgeting rule of thumb with no standard definition; versions online tie the home price to about three times income and set limits on savings and monthly costs. In Boston it breaks down fast, because local prices are high relative to incomes. Use any rule of thumb as a starting filter, then get pre-approved and run your actual numbers: payment, taxes, insurance, fees, and reserves.
What Are the Four C's of Buying a House?
The four C's are a common way to describe how lenders evaluate a mortgage application: Credit (your score and payment history), Capacity (your income against your debts, measured as a debt-to-income ratio, with limits that vary by loan program), Capital (cash for the down payment, closing costs, and reserves), and Collateral (the property, and whether the appraisal supports the price). Where you're weakest shapes your offer strategy.
What Are the Biggest Red Flags When Buying a House?
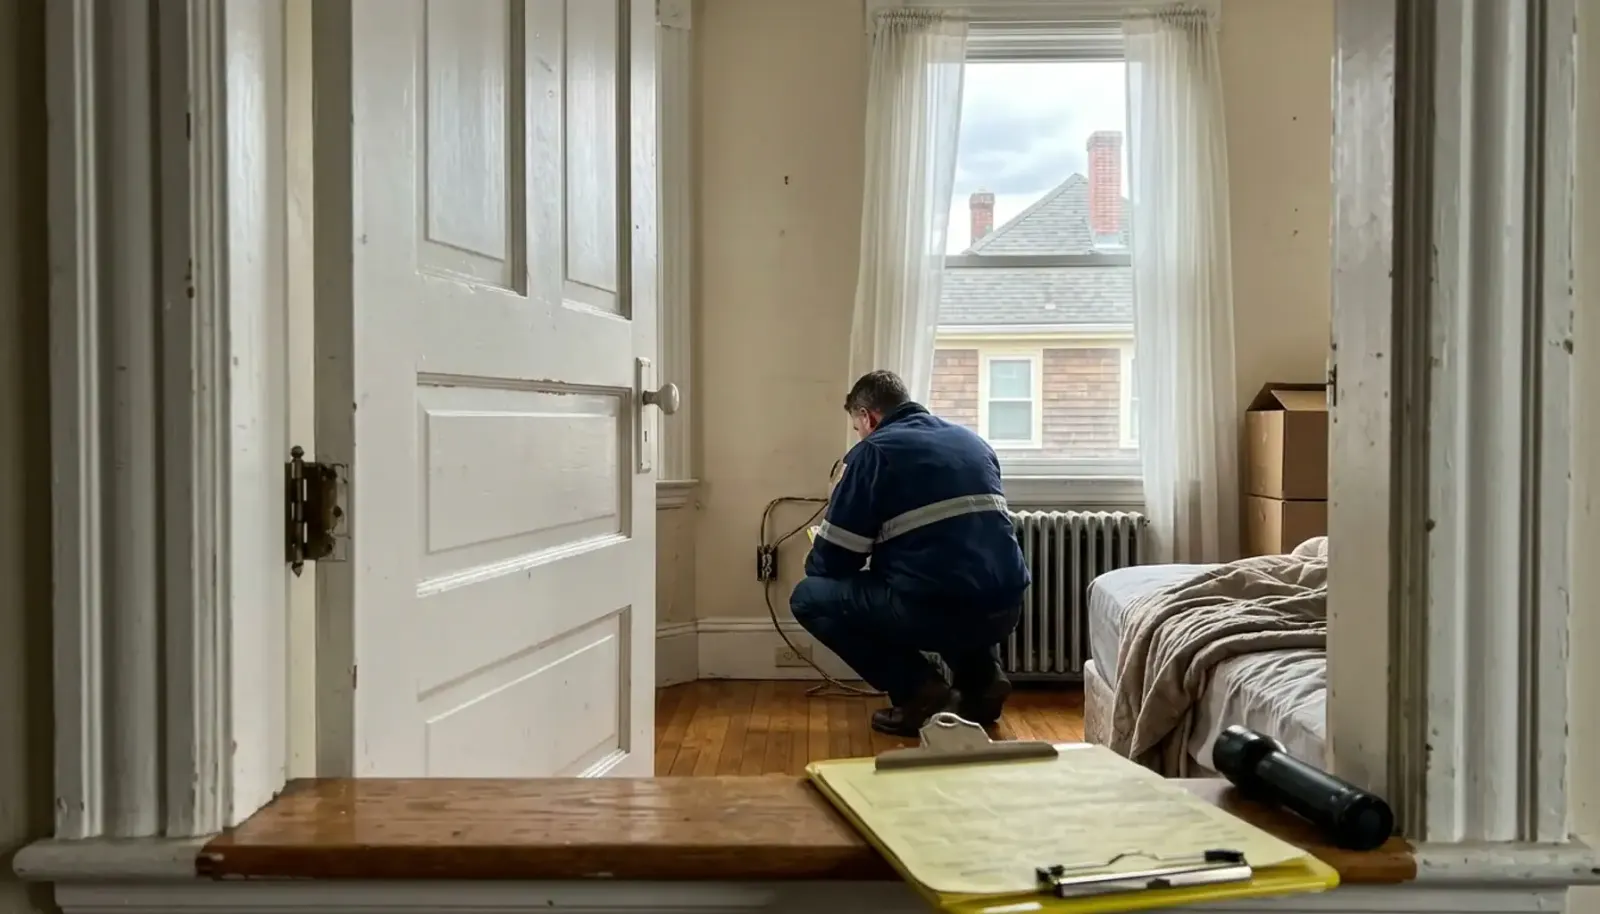
Physical red flags include foundation cracks wider than a hairline, water staining in basements or ceilings, musty odors suggesting moisture, knob-and-tube wiring (found in some older Boston homes and something insurers ask about), sagging rooflines, and heating systems near the end of their life. None is automatically a deal-killer, but each needs to be understood and priced.
Paperwork red flags include unpermitted additions, unclear title history, missing certificates of occupancy for converted units, and, for multi-family properties, leases that don't match what you were told.
Pressure red flags include being pushed to skip the inspection or to remove contingencies before you've seen the results. For contracts signed after October 15, 2025, 760 CMR 74.00 bars sellers and their agents from conditioning acceptance on a buyer waiving or limiting a home inspection on 1 to 4 unit homes, condos, and co-ops, with narrow exemptions. If someone suggests otherwise, treat that as a red flag.
| Red Flag Category | Example | What to Do |
|---|---|---|
| Physical | Water stains, foundation cracks, old wiring | Have a licensed home inspector, and a contractor where needed, estimate the cost before you negotiate |
| Paperwork | Unpermitted additions, mismatched leases | Request permit history and lease copies before your inspection contingency expires |
| Pressure | Being asked to waive the inspection or rush contingencies | Know your rights under Massachusetts rules and involve your agent and attorney right away |
What Do Boston Buyers Need to Know About Lead Paint?
That the seller owes you specific lead paint notices before you sign, and that some older homes need deleading. Many Boston homes were built before 1978, so lead paint rules come up often:
- Before you sign a Purchase and Sale Agreement, the seller must give you the Massachusetts Property Transfer Lead Paint Notification and disclose any known lead hazards (M.G.L. c.111 §197A).
- For pre-1978 housing, federal rules require the seller to disclose known lead paint, give you the EPA pamphlet, and offer a 10-day period for a lead inspection or risk assessment, which can be changed or waived in writing.
- If a child under six lives in a home with lead hazards, the owner must delead it. A new owner has 90 days to comply (M.G.L. c.111 §197).
Lead inspections and deleading are separate from a standard home inspection, so budget for them on older homes.
How Much House Can You Actually Afford Beyond the Down Payment?
True affordability includes closing costs, property taxes, insurance, condo fees where they apply, ongoing maintenance, and a repair reserve. Buyer closing costs in Massachusetts commonly run about 2% to 5% of the price; on a $500,000 purchase that's $10,000 to $25,000 (see the closing costs breakdown). A common rule of thumb for maintenance is about 1% of the home's value a year, roughly $5,000 on that $500,000 home, and older Boston housing often needs more. The inspection report becomes your negotiating document, not a formality.
What Should Be on Your Home Inspection Checklist?
A home inspection should cover the roof, foundation, electrical panel and wiring type, plumbing, heating and cooling, signs of water in the basement or attic, and windows, and for multi-family properties, each unit's systems. Insist that every unit of a two- or three-family is inspected. A standard inspection doesn't include mold or other environmental testing, so ask about those separately if you're concerned. If your agent isn't your exclusive buyer's agent, Massachusetts law doesn't let them directly recommend a specific inspector.
How Do You Actually Decide on a House in Boston?
Confirm your budget, rank your must-haves, get the inspection, price repairs, set a walk-away number, and check days on market.
- Confirm your real number first. Get pre-approved, not just pre-qualified; sellers treat them very differently.
- Rank must-haves separately from nice-to-haves. Location and structural condition should outrank finishes. You can renovate a kitchen; you can't move a foundation.
- Get the inspection. It's your right, and in Massachusetts the seller can't make you give it up to get your offer accepted.
- Price the repairs before you negotiate. "The roof looks old" isn't leverage. A contractor's written estimate is.
- Set your walk-away number before you fall for the house, not during a bidding war.
- Look at days on market, not just price. Across Boston from September 2025 through August 2026, homes that sold within 30 days of listing went for a median 100% of asking, while homes on the market more than 60 days sold for a median 96.9% of their final asking price and 92.6% of their original price (MLS PIN via Repliers). A listing that has been sitting often leaves more room to negotiate.
FAQ
What is the 3-3-3 rule for buying a house?
It's an informal rule of thumb with several versions, usually tying price to about three times income and capping savings use and monthly costs. Treat it as a rough filter, not a rule, especially in Boston.
What are the four C's of buying a house?
Credit, Capacity, Capital, and Collateral: your credit history, your income against your debts, your cash for the purchase and reserves, and the property's appraised value.
What salary do you need for a $400,000 house?
It depends on your down payment, interest rate, debts, taxes, and insurance, so there's no single answer. A lender can tell you what payment you qualify for; decide separately what payment you're comfortable with.
What are the biggest red flags when buying a house?
Signs of water or foundation trouble, outdated wiring, unpermitted work, leases that don't match what you were told, and any pressure to give up your inspection rights. Each needs to be priced and negotiated before you commit.
Do I have to get an inspection when buying a house in Massachusetts?
No law requires you to inspect, but for contracts signed after October 15, 2025, sellers can't condition acceptance on you waiving or limiting the inspection on most 1 to 4 unit homes, condos, and co-ops. Skipping it is your choice to make after acceptance, not the seller's.
Is it better to buy a condo or a multi-family property in Boston?
It depends on your goals. A condo usually means less maintenance responsibility but a monthly fee and shared building decisions. A multi-family can bring rental income and more control, along with tenants to manage and the whole building to maintain.
The bottom line: buying a house in Boston goes best when you know your real budget, get the inspection, price any problems before you negotiate, and set your walk-away number before you fall for the house.
Sources
- 760 CMR 74.03, inspection waiver limits: https://www.law.cornell.edu/regulations/massachusetts/760-CMR-74-03
- 760 CMR 74.04, exemptions and October 15, 2025 applicability: https://www.law.cornell.edu/regulations/massachusetts/760-CMR-74-04
- M.G.L. c.111 §197A, lead paint notification at sale: https://malegislature.gov/Laws/GeneralLaws/PartI/TitleXVI/Chapter111/Section197A
- M.G.L. c.111 §197, deleading obligation: https://malegislature.gov/Laws/GeneralLaws/PartI/TitleXVI/Chapter111/Section197
- EPA, Real Estate Disclosures about Potential Lead Hazards: https://www.epa.gov/lead/real-estate-disclosure
- Boston sale price vs asking by days on market: MLS Property Information Network (MLS PIN) via Repliers, September 2025 through August 2026
Have questions? Let's connect.
About Juan Murray
Juan Murray is a Boston broker associate with more than 30 years of experience helping buyers, sellers, and investors across Greater Boston, personally leading every transaction from the first conversation through closing.
RE/MAX Real Estate Center · (978) 581-0801
Equal Housing Opportunity. Juan Murray is licensed as a Broker in Massachusetts, regulated by the Massachusetts Board of Registration of Real Estate Brokers and Salespersons. This article is general information only and does not constitute legal, tax, or financial advice. Confirm your specific costs and obligations with your closing agent, tax advisor, or lender.